Leverage your superannuation to invest in high-yield Australian property.
Whether its returns that come from capital gains or high rental income, SMSF property lending boosts your retirement wealth by merging physical real estate with concessional super fund tax advantages under compliant Limited Recourse Borrowing Arrangements (LRBA).
Why Australian investors and business owners borrow inside an SMSF.
Self-Managed Super Funds provide unparalleled control over your wealth accumulation, tax efficiency, and commercial property equity.
15% Concessional Super Tax
Net rental earnings are taxed at 15% inside super, dropping to 0% capital gains tax once in pension phase.
Limited Recourse (LRBA)
Lender security is strictly quarantined to the purchased property; all other super assets remain completely shielded.
Business Real Property (BRP)
Business directors can acquire their commercial warehouse or office via their SMSF and lease it back to their company.
Specialist SMSF Lender Panel
Direct panel accreditation with Thinktank, Liberty, La Trobe Financial, Firstmac, Granite, and non-bank funds.
Structured borrowing engineered for compliant super wealth growth.
Borrowing inside super requires specialized compliance, dedicated Bare Trust legal frameworks, and precise lender policy matching. Explore our four dedicated SMSF property debt structures below.

Residential SMSF Property Loans
Acquire residential houses, townhouses, and metro apartments within your super.
Investing in residential real estate through your Self-Managed Super Fund provides a tangible wealth creation pathway. All rental income and capital gains remain sheltered inside the fund under the ATO's 15% super tax regime. Under superannuation law, residential properties must satisfy the 'sole purpose test' and be rented strictly to unrelated third-party tenants.
Commercial SMSF Property & Warehouses
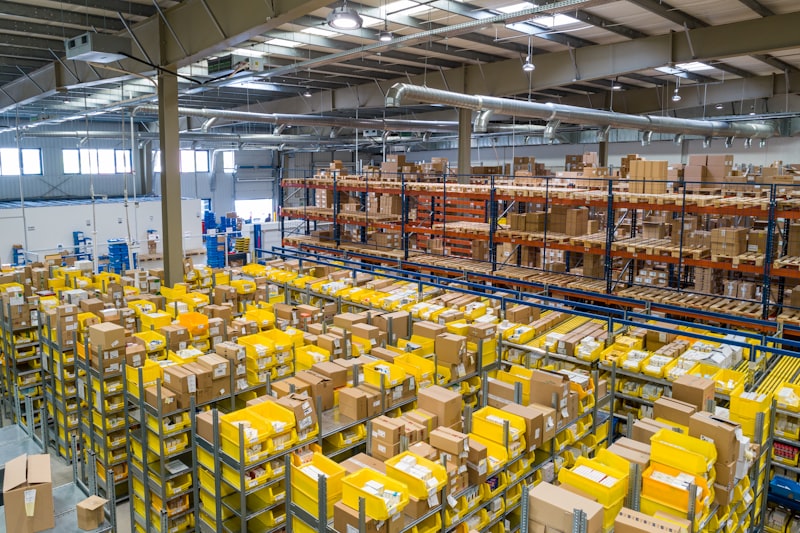
Industrial warehouses, manufacturing facilities, and medical suites within super.
Commercial property is exceptionally popular for SMSF investors due to robust commercial net yields (typically 6% to 8%+), long lease terms, and outgoing recovery agreements. Whether purchasing a freestanding logistics warehouse, a strata industrial unit, or a professional medical suite, we secure competitive SMSF commercial terms across specialist non-bank lenders.
Business Real Property (Lease-Back to Your Business)
Purchase your own trading business premises and lease it back to your operating entity.
Under Australian superannuation law, Business Real Property (BRP) is an exclusive exemption: your SMSF can legally purchase the commercial premises or warehouse from which your own business operates. Your trading company pays commercial market rent directly to your SMSF, transforming a commercial overhead into tax-effective retirement equity.
SMSF Loan Refinancing & Rate Reductions
Transition out of older, high-interest SMSF facilities to competitive modern rates.
Many Australian SMSFs secured loans when the Big Four banks dominated the sector with rigid terms and high margins. Today, active specialist SMSF lenders offer significantly tighter rate spreads and flexible borrowing covenants. Refinancing your SMSF loan can reduce your fund's monthly cash outflow, improve liquidity reserves, and protect super balances.
Understanding Australian SMSF Borrowing Rules
Borrowing within superannuation is heavily governed by the Australian Taxation Office (ATO) and the Superannuation Industry (Supervision) Act (SIS Act). We guide you through the essential compliance pillars.
Limited Recourse Borrowing (LRBA)
By Australian law, an SMSF loan must be an LRBA. If the super fund defaults on mortgage repayments, the lender's rights are strictly confined to the mortgaged property. All other super assets (shares, cash buffers, other properties) are completely quarantined and legally protected.
Bare Trust (Holding Custodian)
A separate legal entity known as a Bare Trust (or Security Custodian) must be established to hold the legal title of the property on behalf of the SMSF until the loan is fully repaid. Once the final mortgage payment is made, legal title transfers cleanly to the SMSF trustee.
Single Acquirable Asset Rule
An SMSF loan can only be used to acquire a single title asset (or identical multiple titles under strict unified zoning). Funds cannot be borrowed under an LRBA to subdivide, develop, or substantially construct a building on vacant land.
Post-Settlement Liquidity Buffers
Most specialist SMSF lenders require the super fund to retain a post-settlement liquidity buffer (typically 5% to 10% of the loan amount or a minimum of $20,000–$50,000 in cash or listed equities) to ensure continuous mortgage servicing during tenant transitions.
Need help structuring your SMSF property acquisition?
Our accredited SMSF finance specialists work closely with your accountant, financial planner, and solicitor to ensure seamless LRBA execution and optimal borrowing terms.